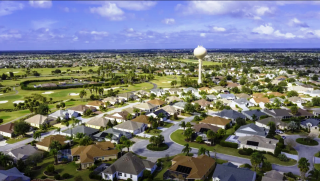
|
Article Courtesy of
Yahoo Finance
By Mike Barrington
Published November 15, 2026
|
What a Couple Actually Spends Living in The Villages
To start, we will use the average U.S. household spending of $78,535 a year. If
you adjust this number for Florida's expense index of 103.414, a couple spends
about $81,200. Now assume a home with no mortgage, without golf frontage, worth
about $400,000. and a median effective property tax rate is 1.13%.
|
Florida ranks 1st on individual income
tax in the 2025 State Tax Competitiveness Index because it
has no personal income tax, so the only tax on IRA
withdrawals is federal. On property tax, it ranks 21st, and
that is the bill a golf lot makes bigger.
What the Fairway Behind the Lanai Really Costs
It should go without saying that golf frontage often sells
at a premium over similar homes. The amenity fee and the CDD
bond stay the same whether the lot backs to a fairway or a
street. One resident shared a real example: in his
neighborhood, new homes backing to an executive course sold
for $135K more than matching homes across the street in
2011.
|
|
|
Golf itself costs residents relatively little. Residents get
free green fees on the executive courses. A cart only costs $8.00 to $12.00 per
round, or a trail pass at $21.77 a month. Every resident gets that access no
matter where the house sits. The lot's annual cost would cover about 577 cart
rounds at the higher trail fee. Frontage buys a view, plus stray balls hitting
lanai screens and less privacy.
Resale data offers limited evidence that the golf premium holds its value over
time. The FHFA index for Wildwood-The Villages rose 36.13% over five years and
2.61% over the past year, but it tracks the whole metro and does not break out
golf lots. Funding the premium can also raise Medicare costs: a lump-sum IRA
withdrawal that drives joint income above $218,000 raises Part B to $284.10 per
person two years later.
What It Takes to Make the Golf Lot Pencil Out
Without frontage, a couple collecting average Social Security needs about $1.02
million to $1.17 million, drawn at 4% to 3.5% from a diversified mix of index
funds and a short Treasury ladder that covers a few years of withdrawals. With a
$135,000 golf lot, the number rises to roughly $1.35 million at 3.5%. The lot
costs about $6,900 a year, which matters differently for two people who play
several times a week and value the view.
Without frontage, a couple collecting average Social Security needs about $1.02
million to $1.17 million, drawn at 4% to 3.5% from a diversified mix of index
funds and a short Treasury ladder that covers a few years of withdrawals. With a
$135,000 golf lot, the number rises to roughly $1.35 million at 3.5%. The lot
costs about $6,900 a year, which matters differently for two people who play
several times a week and value the view.
Buyers who golf less often get the same executive-course access from a house
across the street, with the $135,000 remaining in the portfolio. Before signing,
run the same math on the actual premium for the specific address (we made the
full case for an income-first alternative to the 4% rule in a free guide). The
premium carries ongoing costs in property tax, in income the portfolio does not
produce, and in a higher savings target for as long as the couple owns the
house. |